A portfolio is the collection of investments you hold together: shares, ETFs, managed funds, super, cash. When you invest in a portfolio you spread your money across several investments, which reduces the damage any single one can do. It is worth understanding early, because time is the part you cannot buy back later, so small, steady amounts have decades to compound.
Some apps hand you a ready-made diversified portfolio. inaam is an ASIC-regulated Australian example: one registered fund holding 23 companies across five impact themes, customised by you. The subscription is $10 a month, which is $120 a year, and the minimum to invest in the fund is $100. Sign-up happens in the app. General information only, not financial advice. Consider the PDS and TMD before investing.
You downloaded an investing app and put in $50. There is a screen that says your portfolio, with a number and a line graph. You have no idea what you are looking at, but the line went up slightly, so that feels good.
That is where most people start, and that is fine. A portfolio is a simple idea that almost nobody explains properly. Understanding what one is, and how to think about building one, puts you in a different position.
what a portfolio is in investing
A portfolio is the total collection of everything you have invested in: shares, ETFs, bonds, super, cash in a savings account, crypto if you hold any, property if you own any.
This matters because individual investments go up and down. One share might drop 15% in a week. Your portfolio is the bigger picture. If the rest of your investments held steady or went up, that 15% fall barely moves the needle on the total.
Investopedia’s portfolio guide covers the technical definition. The practical version is simpler: your portfolio is the answer to where is all my money.
the definition that sticks
everything, in one view
The portfolio is the app balance plus the super plus the savings account plus anything else you own. Until you can see all of it on one page, you are making decisions on a fraction of the picture.
why it matters even if you only have $500
There is a common assumption that portfolios are for people with money. If you have $200 in an investing app and $15,000 in super, you already have a portfolio worth $15,200. Most people do not think of their super as part of their investment picture, and it is usually the biggest piece.
Understanding your portfolio early gives you two advantages:
- You see the full picture. You can tell whether everything you hold is working together.
- You make better decisions. When you know what you already own, you do not accidentally double up or leave large gaps.
If super is the biggest piece and you have never looked at it, super basics is the ten minute version.
what goes inside a portfolio
Several types of asset can sit inside a portfolio. You do not need all of them, especially at the start. Knowing what they are helps you understand what people mean when they say asset allocationHow your money is split across the different types of investment you hold. The split does more work than the individual picks..
| what it is | risk level | |
|---|---|---|
| shares (stocks) | Owning a small piece of a company. Value moves with company performance and market sentiment. | Medium to high |
| ETFs | A bundle of shares or bonds in one trade. Instant diversification. We cover these in the ETF guide. | Medium |
| bonds | Lending money to a government or company. They pay you interest on a schedule. More stable than shares. | Low to medium |
| superannuation | Your employer puts money in and it gets invested on your behalf. Usually a mix of shares, bonds and property. | Varies by option |
| cash and savings | High-interest savings accounts or term deposits. Low return, low risk, and you can reach it immediately. | Low |
| crypto | Digital assets like Bitcoin or Ethereum. Highly volatile, and not regulated the same way as traditional investments in Australia. | Very high |
diversification, the concept that matters most
You will hear this word constantly. It means spreading your money across different types of investment so that if one drops, the others hold you up.
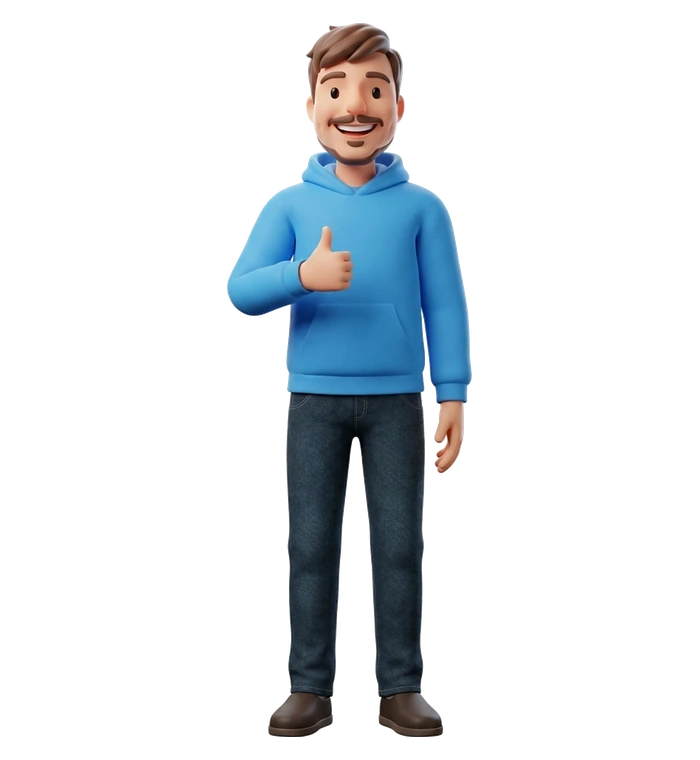
all in on one name
tom
Puts $3,000 into one tech stock. It drops 40%, and he has lost $1,200.
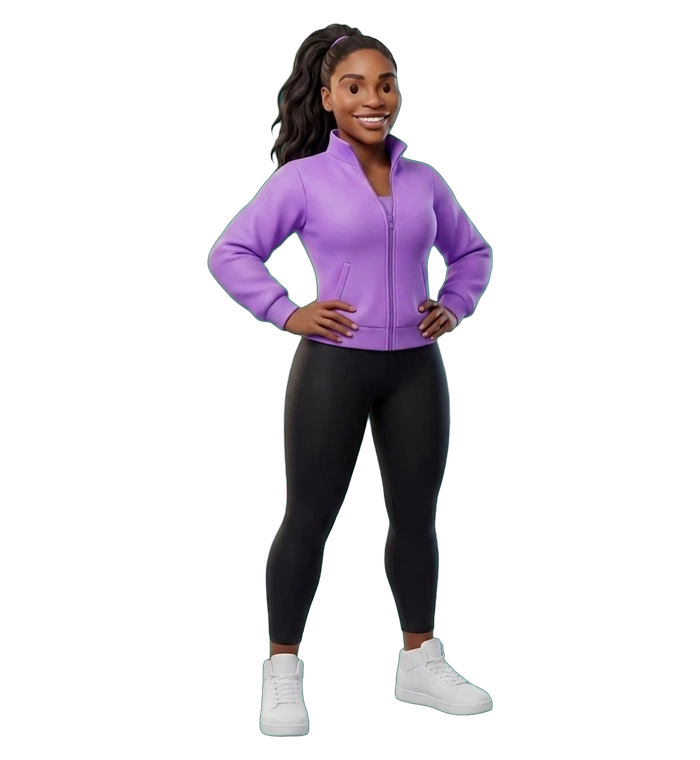
spread across three things
maya
Spreads $3,000 across shares, ETFs and bonds. The same stock drops 40%, but it was only 10% of her total. She is down $120.
The same market event hit both of them, and the outcomes were far apart. That is diversificationSpreading your money across different investments so one bad result cannot sink the lot. It reduces the damage but does not remove the risk.. It does not eliminate risk, because nothing does.
The practical rule: if losing one of your investments would seriously hurt you, you are not diversified enough.
the three questions your portfolio should answer
A good portfolio answers three questions.
1. what am i trying to do?
Are you saving for a house deposit in three years, or building long-term wealth over twenty? The answer changes what you should hold. Short timelines need lower-risk assets like bonds and cash. Longer timelines can carry more shares and ETFs, because you have time to ride out the dips.
2. does this reflect what i care about?
If you care about the environment and your super fund is invested in fossil fuels, there is a gap between what you say and where your money goes. The Responsible Investment Association Australasia (RIAA) publishes a list of certified responsible investment funds in Australia, which is a good place to start looking for options.
values, in practice
the gap is usually in the account you never open
Most people check the investing app weekly and the super fund never. The super fund is where the larger share of your money is already invested, and switching the option inside it takes about ten minutes.
3. am i spreading the risk?
If you own five tech stocks and nothing else, your money is concentrated in one sector. Check whether your portfolio covers different sectors, regions and asset types. Moneysmart’s diversification guide walks through the four asset classes and how to keep a mix of them in balance.
mistakes that trip up first-time investors
- Checking the balance daily. Markets move, and if you are investing for the long term, daily price movements are noise. Quarterly check-ins are enough.
- Ignoring super. Your super is invested, so it counts. If you want your portfolio to match your values, you can switch your super to an ethical option in about ten minutes.
- Copying someone else’s portfolio. Their risk tolerance, timeline and income are not yours. What works for them might be wrong for you.
- Not starting because the amount feels too small. Small amounts paid in regularly, started early, get the one thing you cannot buy later, which is time in the market. The habit does more work than the size of the first deposit. The gap five years makes is illustrated, on a stated return assumption, in what i wish i knew when i started.
- Over-trading. Buying and selling frequently racks up brokerage fees, and the research on patient holding against frequent trading is fairly settled.
what over-trading costs
the quiet cost of doing something
Every trade has a fee and a spread attached to it. A portfolio you leave alone pays none of that, while one you fiddle with pays a small toll each time. Those tolls are the part you can control.
a realistic starting portfolio
If you have a long investment horizon ahead of you, a reasonable starting point might look like this.
| what | why | |
|---|---|---|
| 60% to 70% | Growth: shares and ETFs | A long timeline leaves room to ride out the volatility that comes with growth assets |
| 15% to 20% | Stability: bonds and fixed income | Smooths out the ride when markets dip |
| 10% to 20% | Cash, the emergency buffer | Reachable when you need it, rather than locked in markets |
This is a rough guide rather than a prescription. Your actual split depends on your income, your goals and how much risk you can stomach. If a 20% market fall would make you sell everything, you need more in bonds and cash.
where inaam fits
where we fit
a diversified impact portfolio, built in the app
One registered fund, 23 companies, and five impact themes you customise yourself. Every company is named in the app with the impact data sitting next to it, so you can read what is in the portfolio.
inaam builds a diversified impact portfolio for you. You tell us what you care about through the money values quiz, you customise the five themes, and every company has to clear the same three checks before it can get in. You can see exactly what is in the fund and why each holding is there on how it works.
The subscription is $10 a month, which is $120 a year, and it is separate from the money you invest. The minimum to invest in the fund is $100. Sign-up happens in the app rather than on this website. SMSFs and family trusts are welcome.
If you would rather build your own portfolio and want to understand the building blocks, start with the guide to ETFs and the P/E ratio explainer. If you want the lessons rather than the mechanics, what i wish i knew when i started is the shorter read. You can also see how inaam sits beside other platforms on compare.